[pageLogInLogOut]

#Europe

Fair Taxation: Commission proposes swift transposition of the international agreement on minimum taxation of multinationals

Today, the European Commission has proposed a Directive ensuring a minimum effective tax rate for the global activities of large multinational groups. The proposal delivers on the EU's pledge to move extremely swiftly and be among the first to implement the recent historic global tax reform agreement [1], which aims to bring fairness, transparency and stability to the international corporate tax framework.

Today's proposal follows closely the international agreement and sets out how the principles of the 15% effective tax rate – agreed by 137 countries – will be applied in practice within the EU. It includes a common set of rules on how to calculate this effective tax rate, so that it is properly and consistently applied across the EU.

Executive Vice-President for an Economy that Works for People, Valdis Dombrovskis, said: “By moving quickly to align with the far-reaching OECD agreement, Europe is playing its full part in creating a fairer global system for corporate taxation. This is particularly important at a time when we need to increase public financing for fair sustainable growth and investment and meet public financing needs too – both for tackling the pandemic's aftermath and driving forward the green and digital transitions. Putting the OECD agreement on minimum effective taxation into EU law will be vital for fighting tax avoidance and evasion while preventing a ‘race to the bottom' with unhealthy tax competition between countries. It is a major step forward for our fair taxation agenda.”

Commissioner for Economy, Paolo Gentiloni, said: “In October of this year, 137 countries supported a historic multilateral agreement to transform global corporate taxation, addressing longstanding injustices while preserving competitiveness. Just two months later, we are taking the first step to put an end to the tax race to the bottom that harms the European Union and its economies. The directive we are putting forward will ensure that the new 15% minimum effective tax rate for large companies will be applied in a way that is fully compatible with EU law. We will follow up with a second directive next summer to implement the other pillar of the agreement, on the reallocation of taxing rights, once the related multilateral convention has been signed. The European Commission worked hard to facilitate this deal and I am proud that today we are at the vanguard of its global rollout.”


The proposed rules will apply to any large group, both domestic and international, with a parent company or a subsidiary situated in an EU Member State. If the minimum effective rate is not imposed by the country where a low-taxed company is based, there are provisions for the Member State of the parent company to apply a “top-up” tax. The proposal also ensures effective taxation in situations where the parent company is situated outside the EU in a low-tax country which does not apply equivalent rules.

In line with the global agreement, the proposal also provides for certain exceptions. To reduce the impact on groups carrying out real economic activities, companies will be able to exclude an amount of income equal to 5% of the value of tangible assets and 5% of payroll. The rules also provide for an exclusion of minimal amounts of profit, to reduce the compliance burden in low risk situations. This means that when the average profit and revenues of a multinational group in a jurisdiction are below certain minimum thresholds, then that income is not taken into account in the calculation of the rate.

Background

Minimum corporate taxation is one of the two work streams of the global agreement - the other is the partial re-allocation of taxing rights (known as Pillar 1). This will adapt the international rules on how the taxation of corporate profits of the largest and most profitable multinationals is shared amongst countries, to reflect the changing nature of business models and the ability of companies to do business without a physical presence. The Commission will also make a proposal on the reallocation of taxing rights in 2022, once the technical aspects of the multilateral convention are agreed.

Next steps

The Commission's tax agenda is complementary to, but broader than just the elements covered by the OECD agreement. By the end of 2023, we will also publish a new framework for business taxation in the EU, which will reduce the administrative burden for businesses working across Member States, remove tax obstacles and create a more business-friendly environment in the Single Market.
More News from TEXDATA International

#India ITME 2026

India’s textile industry: Current position, growth targets and industrial development

With ambitious export targets, major investments in manufacturing infrastructure and new international trade agreements, India is pursuing a comprehensive development strategy for its textile and apparel industry. An overview of the industry’s current position, government initiatives, progress achieved and challenges ahead.

#Weaving

“A complex design is only useful if the machine can reproduce it consistently”

Andreas Schnabel, Head of R&D for Technical Weaving Systems at Stäubli, discusses how 3D weaving can create textile reinforcements tailored to the loads within a composite component, where near-net-shape weaving can reduce processing steps and material waste, and what it takes to produce complex structures reliably and economically. He also explains how manufacturers can adapt Stäubli’s modular TF weaving platforms to new applications and how the company’s centre of excellence in Bayreuth supports the transition from research to industrial production.

#India ITME 2026

India ITME 2026: Textile technology meets India's investment ambitions

With ambitious growth targets, government incentive programmes and industrial development initiatives already underway, India is preparing for the next stage of its textile transformation. Against this backdrop, the 12th India ITME, taking place in Greater Noida from 4 to 9 December 2026, arrives at a particularly important moment for machinery manufacturers and textile producers alike.

#ITMA Asia + CITME 2026

ITMA ASIA + CITME 2026: Shanghai prepares for a record edition

With record demand for exhibition space, a strong presence of international technology suppliers and growing interest in automation and intelligent manufacturing, ITMA ASIA + CITME 2026 will provide an important overview of technological developments in the world’s largest textile producing region.

More News on Europe

#Nonwovens

EU imposes definitive anti-dumping duties on Chinese PET spunbond imports

The European Commission has introduced definitive anti-dumping duties ranging from 39.8% to 48.1% on imports of PET spunbond from China. The measures, which entered into force on 31 October 2026, will remain in place for five years and are intended to address unfairly priced imports that have caused injury to European manufacturers. The EU market for these nonwoven materials is valued at approximately €200 million.

#Associations

European and Canadian textile associations call for stronger transatlantic cooperation

Ahead of the EU–Canada Summit in Montréal on 29–30 October 2026, EURATEX, the Canadian Textile Industry Association (CTIA) and the Canadian Apparel Federation (CAF) have issued a joint statement calling for closer industrial cooperation, improved implementation of the CETA trade agreement and stronger partnerships in innovation, sustainability and advanced textile technologies.

#Europe

Strategic policy can drive a clean and competitive European industry

Europe can strengthen its industrial competitiveness while cutting climate and environmental pressures, but progress needs to accelerate. A new report from the European Environment Agency (EEA) finds that the transition of key industrial sectors offers opportunity and explores the policies, investments and enabling conditions needed to drive clean, circular and decarbonised production at scale, delivering prosperity.

#Europe

Textile ETP launches bioeconomy strategy for Europe’s textile industry

On 22 September 2026, Textile ETP's Circular & Biobased Textiles Innovation Hub published its strategy for the biobased and circular transformation of Europe's textile and apparel industry.

Latest News

#ITMA Asia + CITME 2026

Saurer showcases flexible spinning solutions from bale to yarn at ITMA ASIA + CITME 2026

At ITMA ASIA + CITME 2026 in Shanghai, Saurer will demonstrate how its advanced technologies enable maximum flexibility across the entire spinning process, from bale to yarn and twisting. Visitors to hall 6.1, booth A58, can explore solutions designed to optimise production, improve efficiency and help mills respond quickly to changing market demands. Saurer's experts will be available to discuss individual production challenges and tailored solutions.

#India ITME 2026

Uster to present novel solutions at India ITME 2026

Tackling contamination is a critical quality target in yarn production – and Uster now enables spinners to make the right choices for optimized profitability, with top technology, precise data and integrated analysis across the entire process. The new Uster Contamination Control solution and latest Uster Vision Shield 3i put spinners in command of contaminant removal, ensuring yarn quality, minimizing waste and protecting profits. These exciting developments – and even more news – will be featured at India ITME 2026.

#Nonwovens

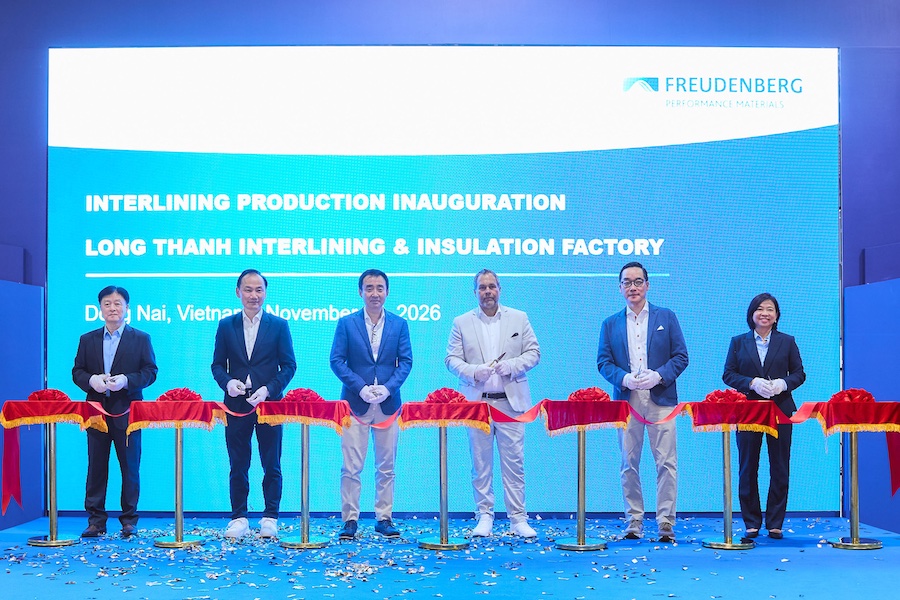
Freudenberg Performance Materials brings interlining production to Vietnam for faster regional supply

Freudenberg Performance Materials Apparel (Freudenberg Apparel) has expanded its manufacturing capabilities in Vietnam with local apparel interlining production at its factory in Long Thanh, Dong Nai. Apparel brands and manufacturers in Southeast Asia can now source both interlinings and comfortemp® thermal insulation from Vietnam, benefiting from shorter lead times, improved supply responsiveness, and consistent quality standards across Freudenberg Apparel’s regional manufacturing network.

#EU Textile Strategy

EURATEX and Egyptian industry groups sign textile cooperation agreement

The European Apparel and Textile Confederation (EURATEX) has signed a memorandum of understanding with the Apparel Export Council of Egypt (AEC), the Textile Export Council of Egypt (TEC) and the Egyptian Exporters Association (EXPOLINK). The agreement sets out plans to help Egyptian manufacturers prepare for EU sustainability requirements, promote investment and strengthen ties between European and Egyptian textile and clothing companies.

TOP